A look at the day ahead in European and global markets
|
|
|
|
By Wayne Cole, Chief Correspondent, Treasury
|
|
|
|
|
It's not been a good start to the week for right-wing politicians, with Brazilian President Luiz Inacio Lula da Silva winning a fourth term and Serbia's Aleksandar Vucic losing to a student-led protest movement.
The Brazilian real is yet to trade, though a Brazilian ETF traded in Tokyo has shed almost 15%, reversing gains made when Senator Flavio Bolsonaro led in the first round of voting. Bolsonaro later refused to concede defeat, saying he would challenge the result.
Next up is Benjamin Netanyahu's Likud party in Israel. All three of the right-wingers were supported by President Trump, whose party faces its own vote test next week with the midterms.
|
|
|
|
Oil price flag for central banks |
Oil pumps operate after sunset outside Vaudoy-en-Brie, near Paris, France, March 18, 2026. REUTERS/Christian Hartmann
|
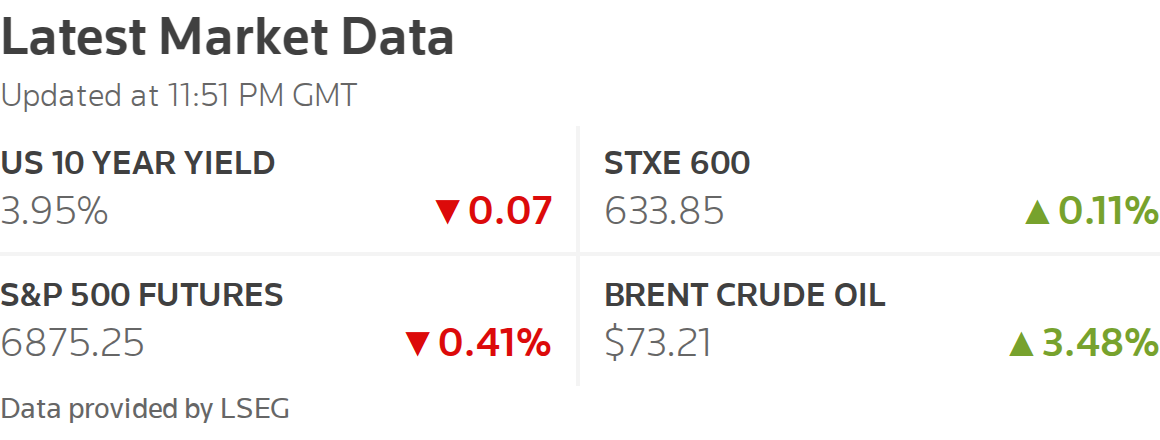
Otherwise, it's been a guarded start in markets with Wall Street futures and most of Asia down slightly. Oil prices have eased somewhat, perhaps in part on reports Qatari mediators were in Tehran on Sunday as part of an effort to de-escalate regional tensions in coordination with the United States.
Then again, Brent futures jumped over 6% last week to their highest weekly close since mid-2022 as Houthi attacks in Saudi Arabia stoked concerns over energy supplies.
Trump on Friday said the US may carry out another military operation against Iran, while Tehran has threatened reprisals including hitting submarine cables.
Such high energy costs mean central bankers meeting this week are likely to sound hawkish, even if they don't tighten this time. Markets are wagering on hikes from central banks in Canada and New Zealand this week, while assuming the US Federal Reserve, Bank of Japan and the European Central Bank will stand pat for now.
|
Graphics are produced by Reuters
|
|
|
|
Hyperscaler earnings watch |
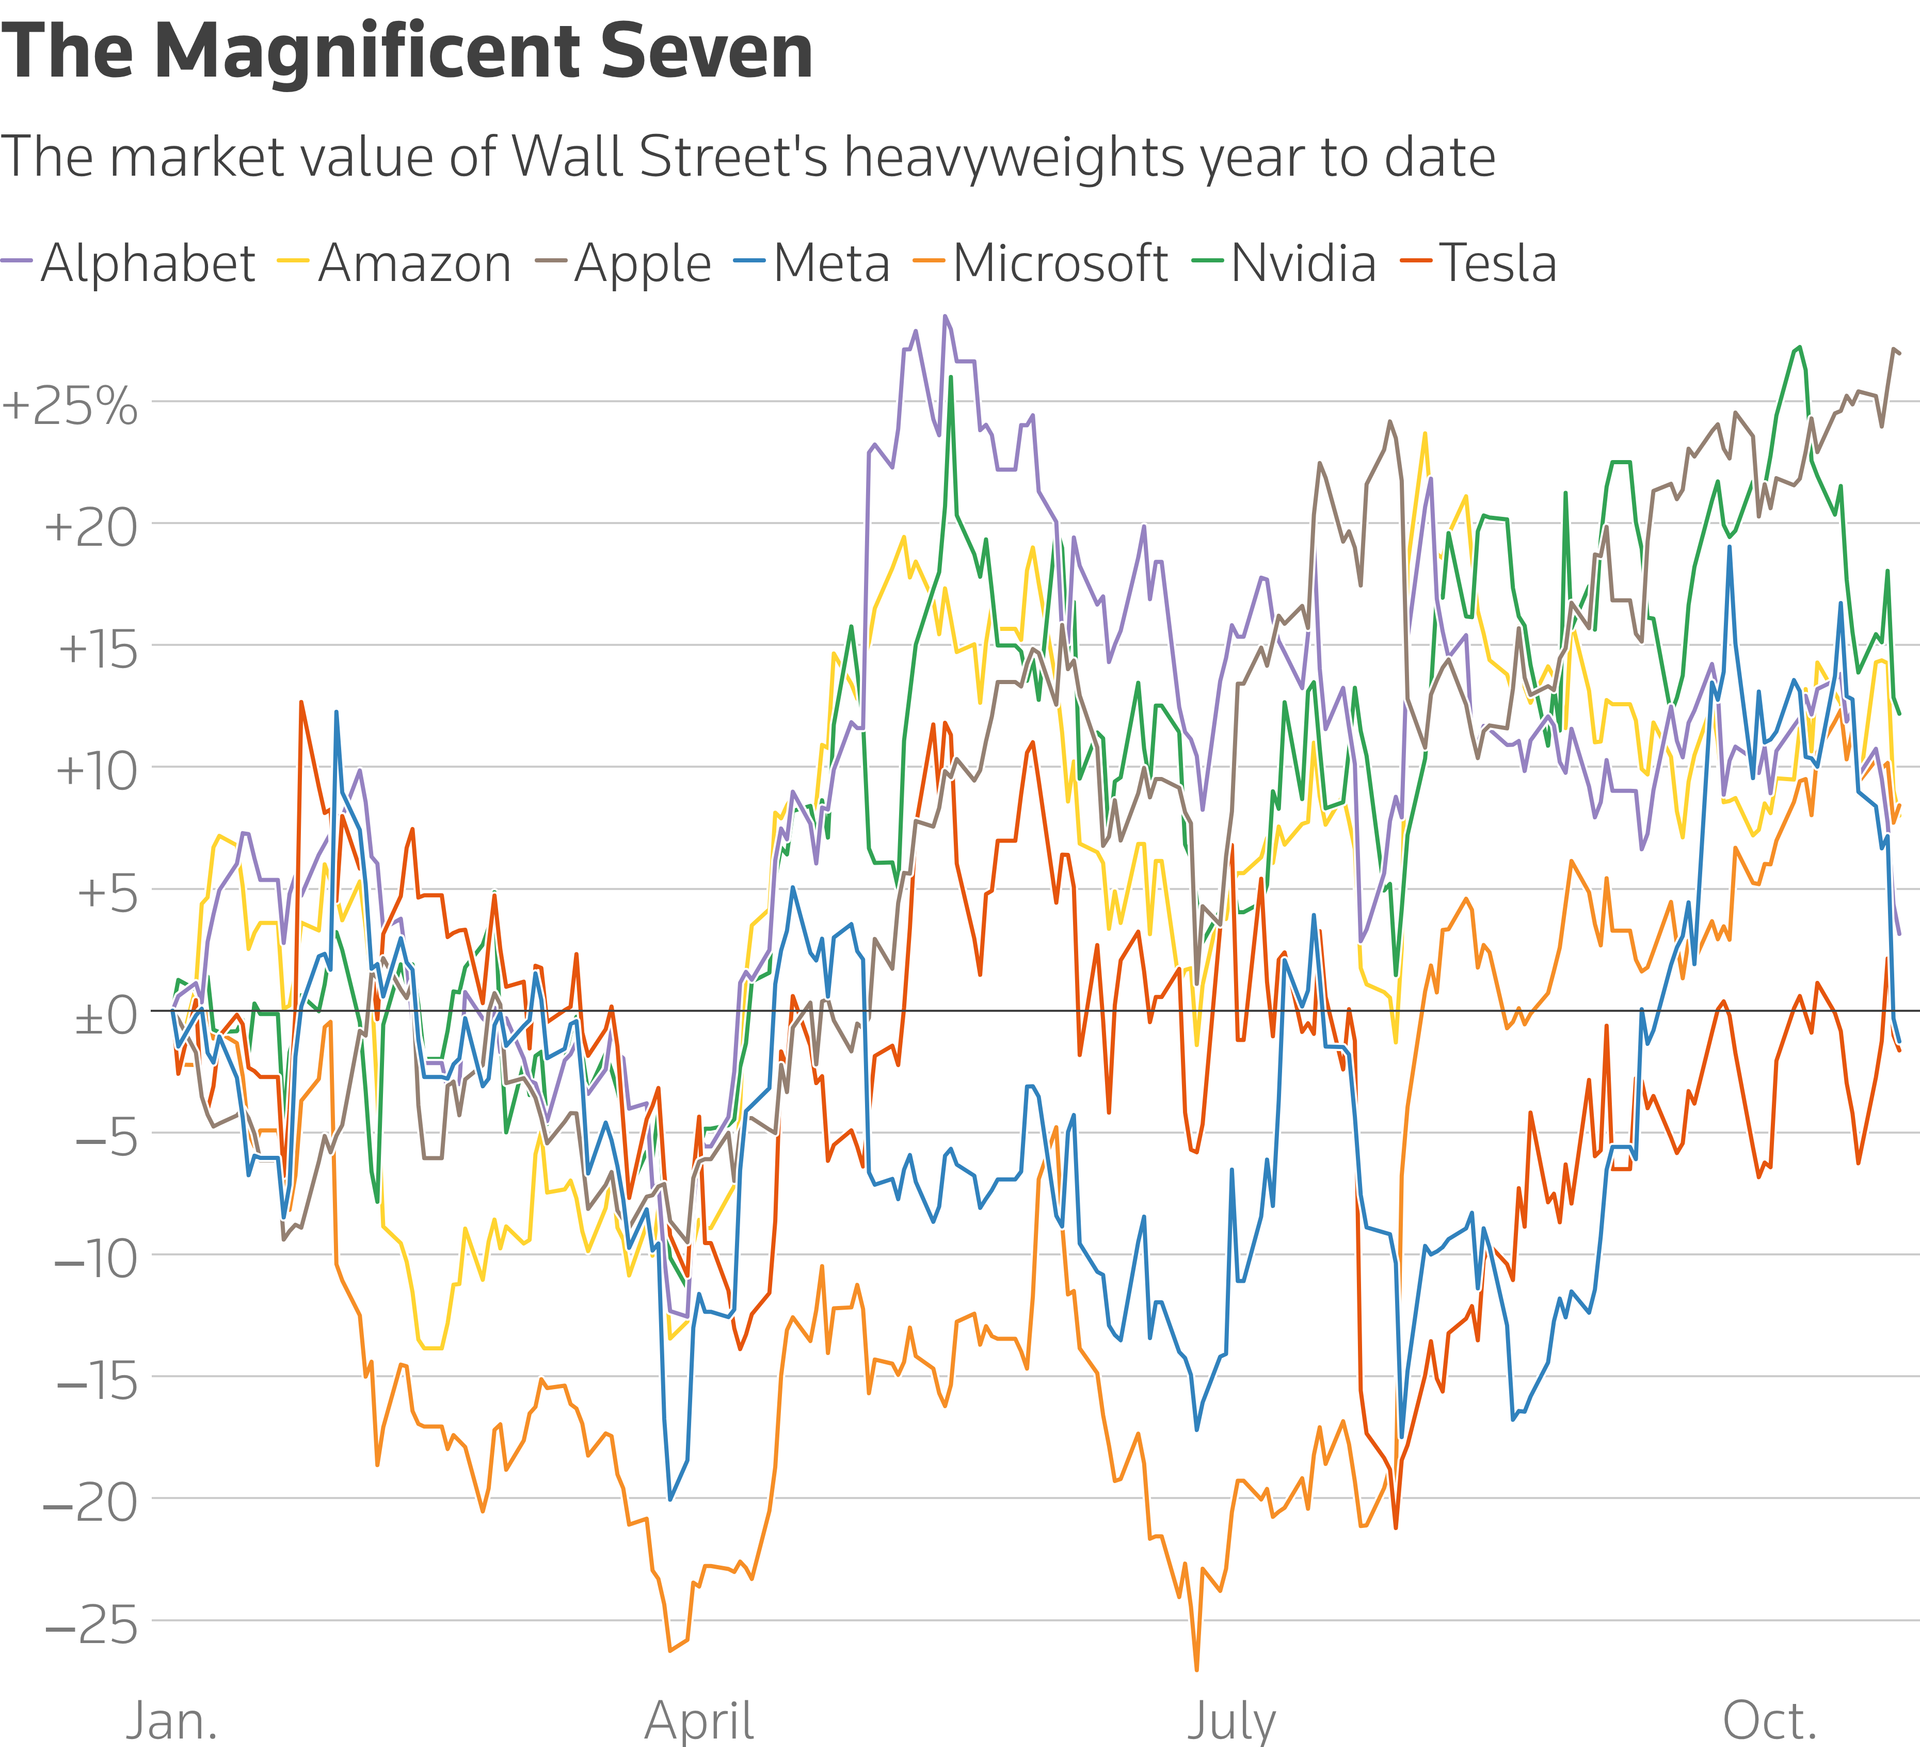
Earnings highlights will include the hyperscalers Alphabet, Microsoft and Amazon, among one-third of S&P 500 companies reporting. Results from Intel and Sandisk also could influence the AI trade.
Consensus on Microsoft is for $90.6 billion in revenue and an adjusted EPS of $4.73, with Amazon at $202 billion in revenue and EPS around $1.97. Alphabet revenue is seen at $128 billion and EPS of $3.00.
In Asia, SK Hynix and Samsung Electronics both report this week. SK Hynix also said it will announce shareholder return measures on Wednesday, responding to a report that it is considering a special dividend of about 16 trillion won ($12 billion).
|
|
|
|
Key developments that could influence markets on Monday: |
|
|
|
Opinions expressed are those of the author. They do not reflect the views of Reuters News, which, under the Trust Principles, is committed to integrity, independence, and freedom from bias.
|
|
|
|
|
|
| |
|
|
Morning Bid is sent every weekday morning. Think your friend or colleague should know about us? Forward this newsletter to them. They can also sign up here. Want to stop receiving this email? Unsubscribe here. To manage which newsletters you're signed up for, click here. This email includes limited tracking for Reuters to understand whether you’ve engaged with its contents. For more information on how we process your personal information and your rights, please see our Privacy Statement. Terms & Conditions |
|
| |
© 2026 Thomson Reuters. All rights reserved.
3 Times Square, New York, NY 10036 |
|
|
|
|
|






No comments:
Post a Comment