A look at the day ahead in European and global markets
|
|
|
|
By Wayne Cole, Chief Correspondent, Treasury
|
|
|
|
|
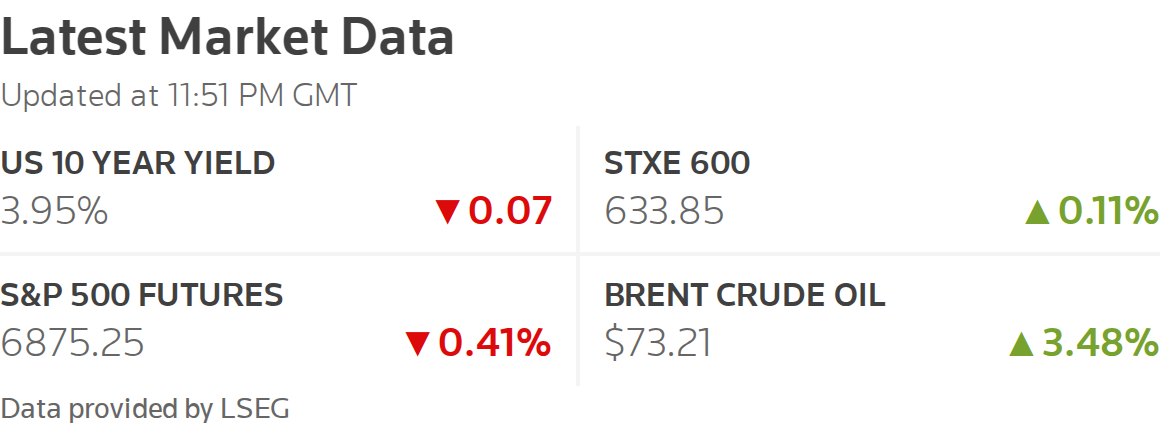
So oil slips on the chance of increased Russian shipments after President Donald Trump waived some sanctions on Moscow, or did he? Trump himself seems unsure, telling reporters, "A lot of you don't know what my decision is yet, but we'll figure it out, and you'll figure it out."
|
|
|
|
Ukraine's kinetic sanctions |
Birds fly over pump jacks at the Airankol oil field operated by Caspiy Neft in the Atyrau region, Kazakhstan, April 20, 2026. REUTERS/Pavel Mikheyev/File Photo
|
Secretary of State Marco Rubio on Saturday claimed officials want more time to evaluate the situation, and Trump would use up to 60 days to assess the economic impact of Russia-related sanctions and tariffs that he waived a day earlier.
In any case, it's not clear Russia could actually increase its oil exports as Ukraine continues its kinetic sanctions, hitting an oil depot and port in St Petersburg, along with another data center and logistics warehouse.
Meanwhile, Iran said an oil tanker caught fire and exploded after striking a naval mine in the southern part of the Strait of Hormuz, while the United Kingdom Maritime Trade Operations (UKMTO) is reporting more attacks on shipping every day.
The disruption has seen rates for tankers hit record highs and lifted insurance charges, adding to the cost of every barrel shipped and to physical delivery prices.
|
Graphics are produced by Reuters
|
|
|
|
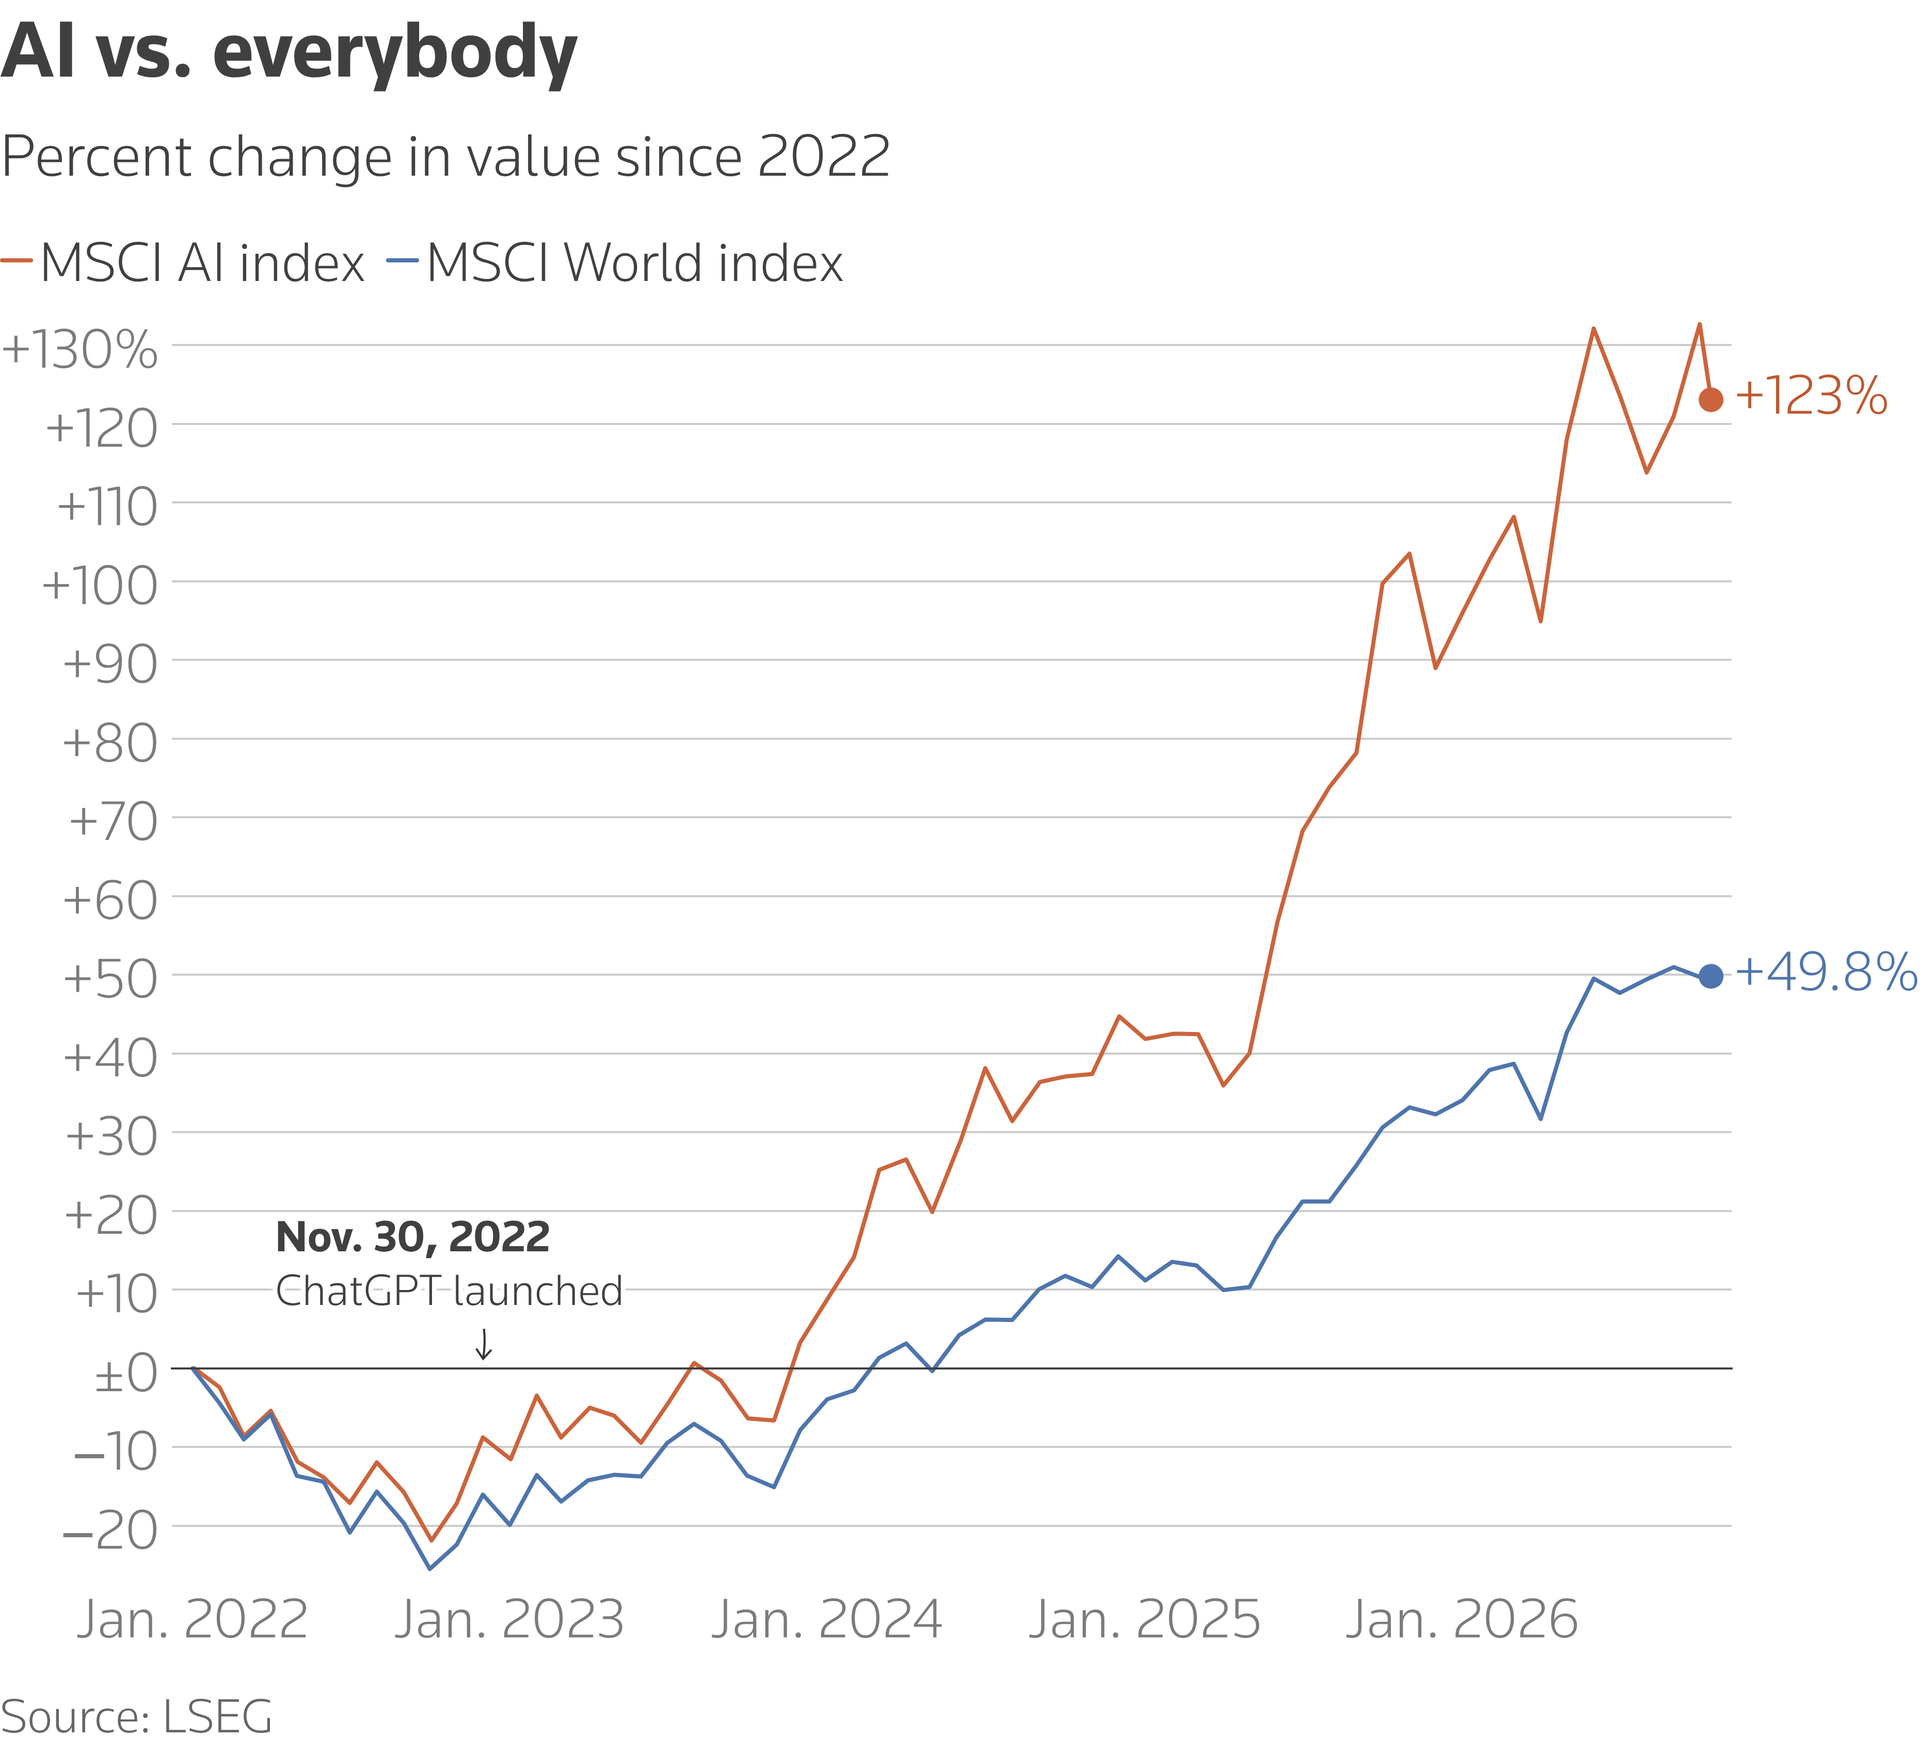
Stocks still jittery over AI |
For now, Brent futures are down around 1.5%, helping Treasuries extend their rally and nudging Wall Street futures higher. Asian stocks are still having jitters over AI and the cost of capital with South Korea off another 0.5% after shedding 14% last week.
China's economy grew 4.5% in the third quarter to just pip forecasts. Retail sales were also better with a rise of 1.1%, while industrial output growth came in on forecasts at 5.5%.
China's yuan firmed to its strongest level since July 2022 at 6.6828, while stocks were down modestly.
Investors will be hoping the wave of company results this week brightens the mood, with the tech sector expected to report earnings growth of 65%. All eyes will be on Meta on Wednesday, when it needs to make $62.5 billion to hit the midpoint of its own revenue guide.
The company already expects to spend $130 billion to $145 billion on capex in 2026, and any increase in that could unsettle investors.
Among the host of companies reporting are Lam Research, Texas Instruments, SpaceX, Tesla and Netflix.
|
|
|
|
Key developments that could influence markets on Monday: |
- US NAHB housing market index for October
|
|
|
|
Opinions expressed are those of the author. They do not reflect the views of Reuters News, which, under the Trust Principles, is committed to integrity, independence, and freedom from bias.
|
|
|
|
|
|
| |
|
|
Morning Bid is sent every weekday morning. Think your friend or colleague should know about us? Forward this newsletter to them. They can also sign up here. Want to stop receiving this email? Unsubscribe here. To manage which newsletters you're signed up for, click here. This email includes limited tracking for Reuters to understand whether you’ve engaged with its contents. For more information on how we process your personal information and your rights, please see our Privacy Statement. Terms & Conditions |
|
| |
© 2026 Thomson Reuters. All rights reserved.
3 Times Square, New York, NY 10036 |
|
|
|
|
|





No comments:
Post a Comment