A look at the day ahead in European and global markets
|
|
|
|
By Ankur Banerjee, Asia Finance & Markets Breaking News Correspondent
|
|
|
|
|
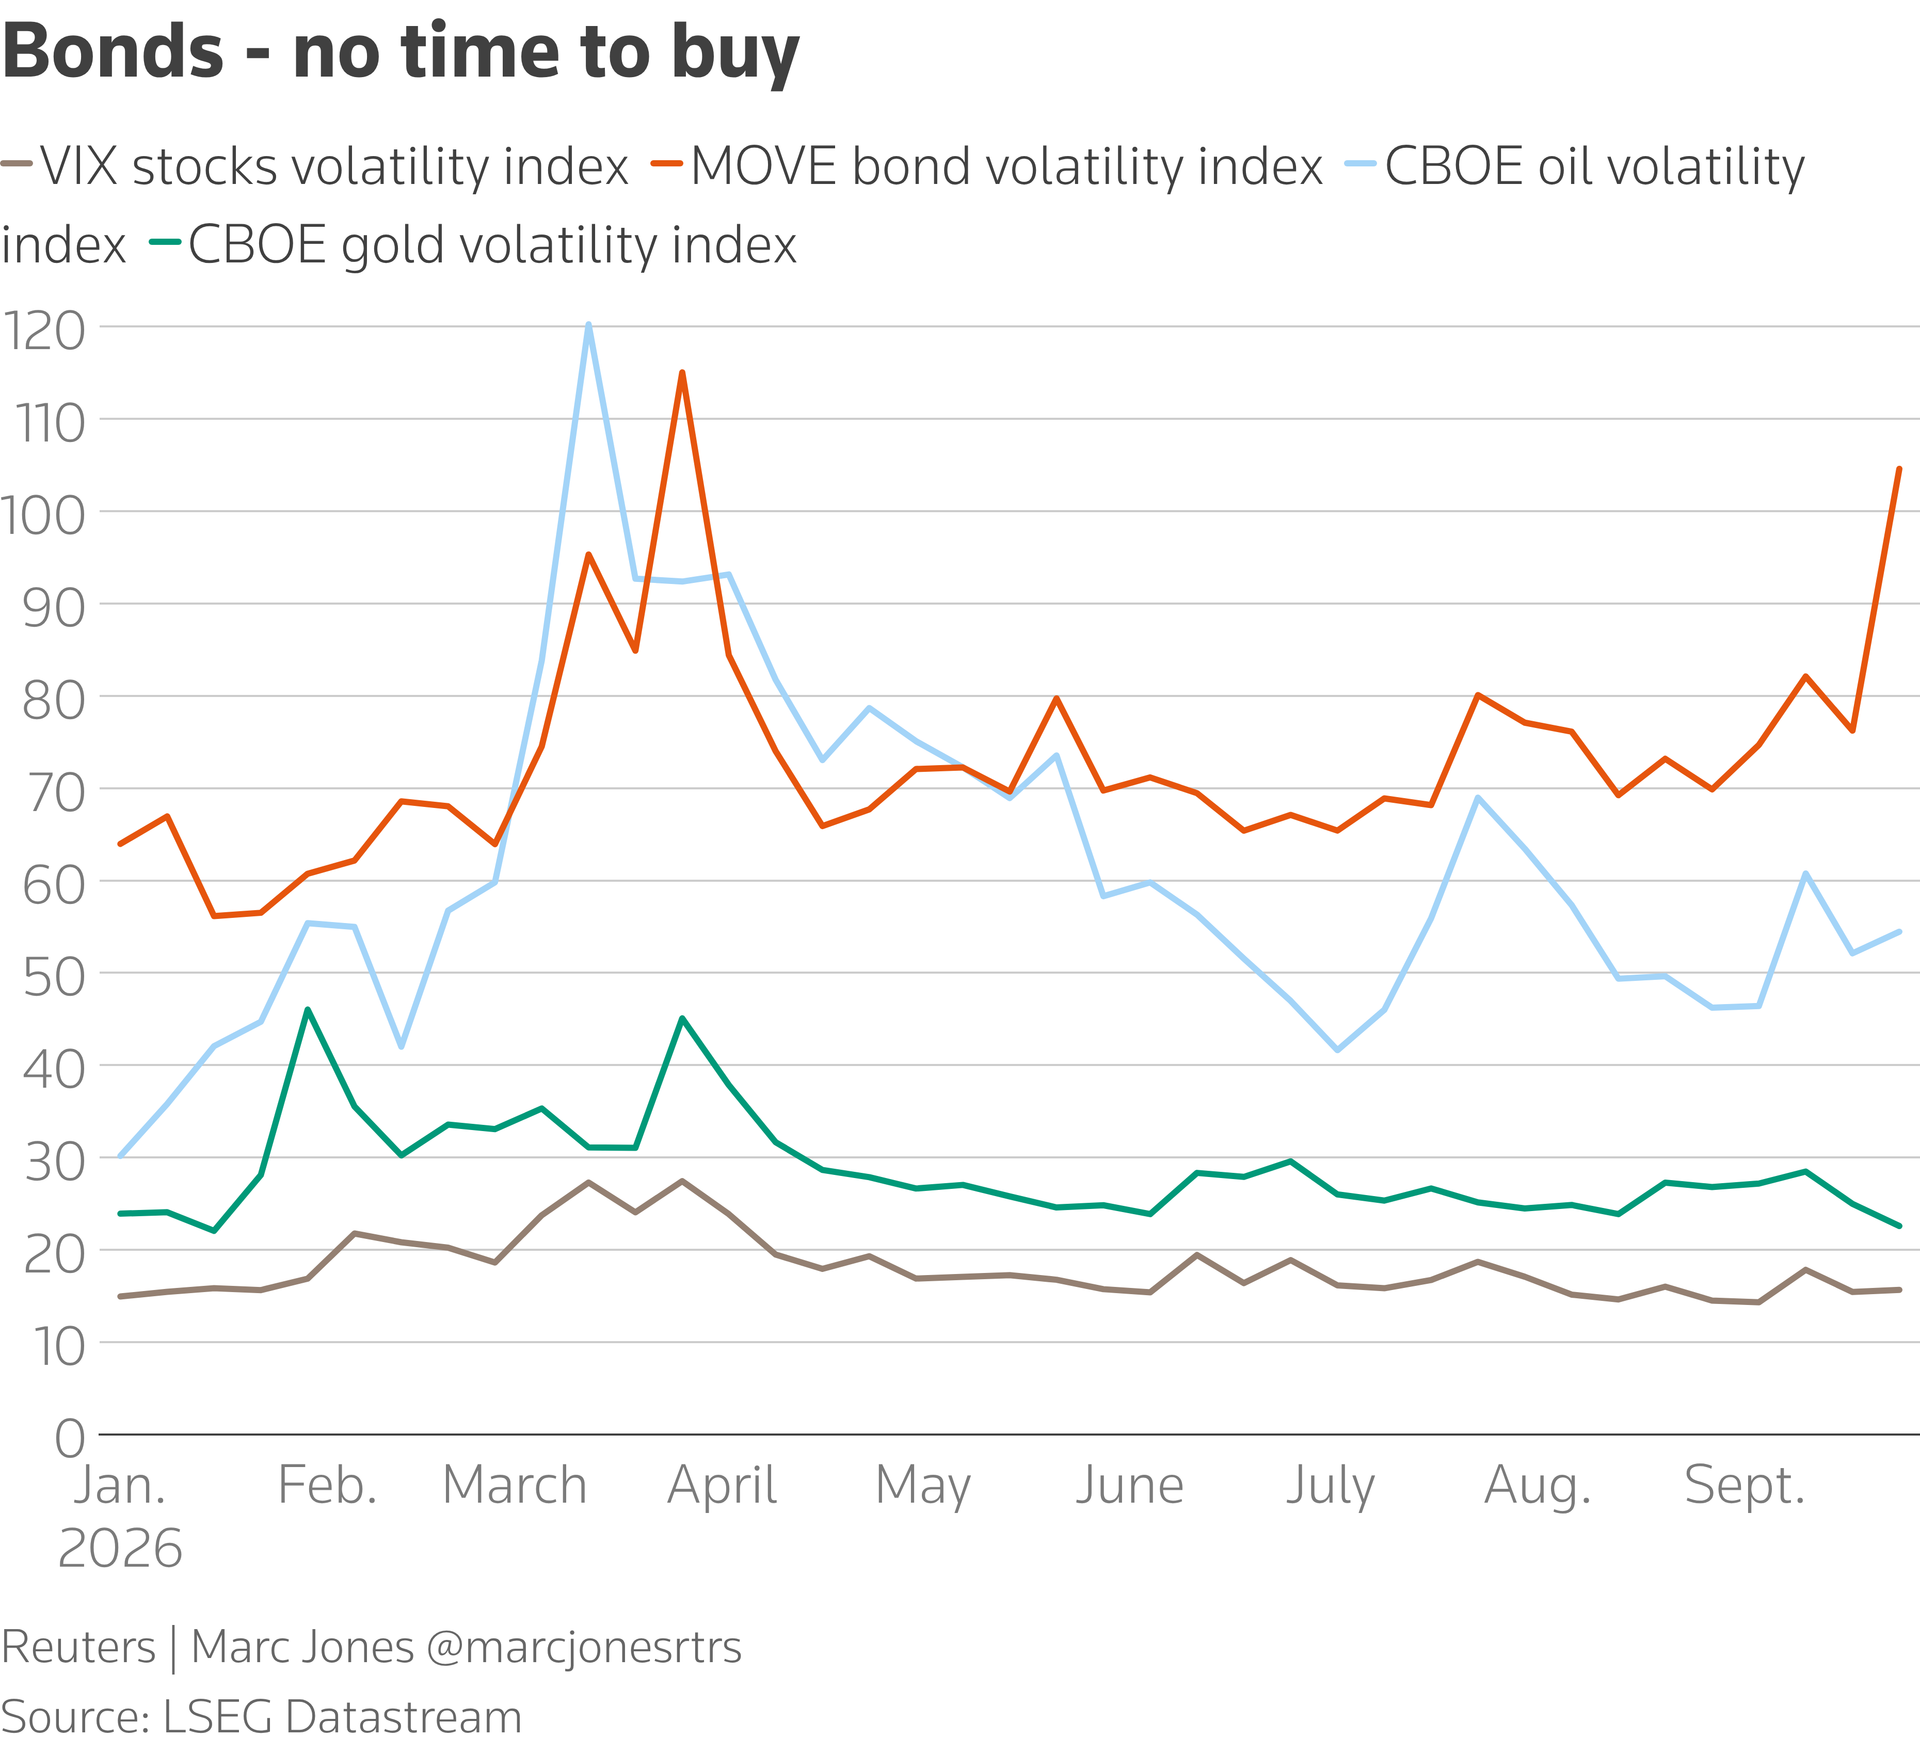
Bond markets are staring at a brutal quarter as inflation risks due to the seven-month-long war in the Middle East heighten fears over a worsening of fiscal health across the globe, driving borrowing costs to levels not seen in decades.
|
|
|
|
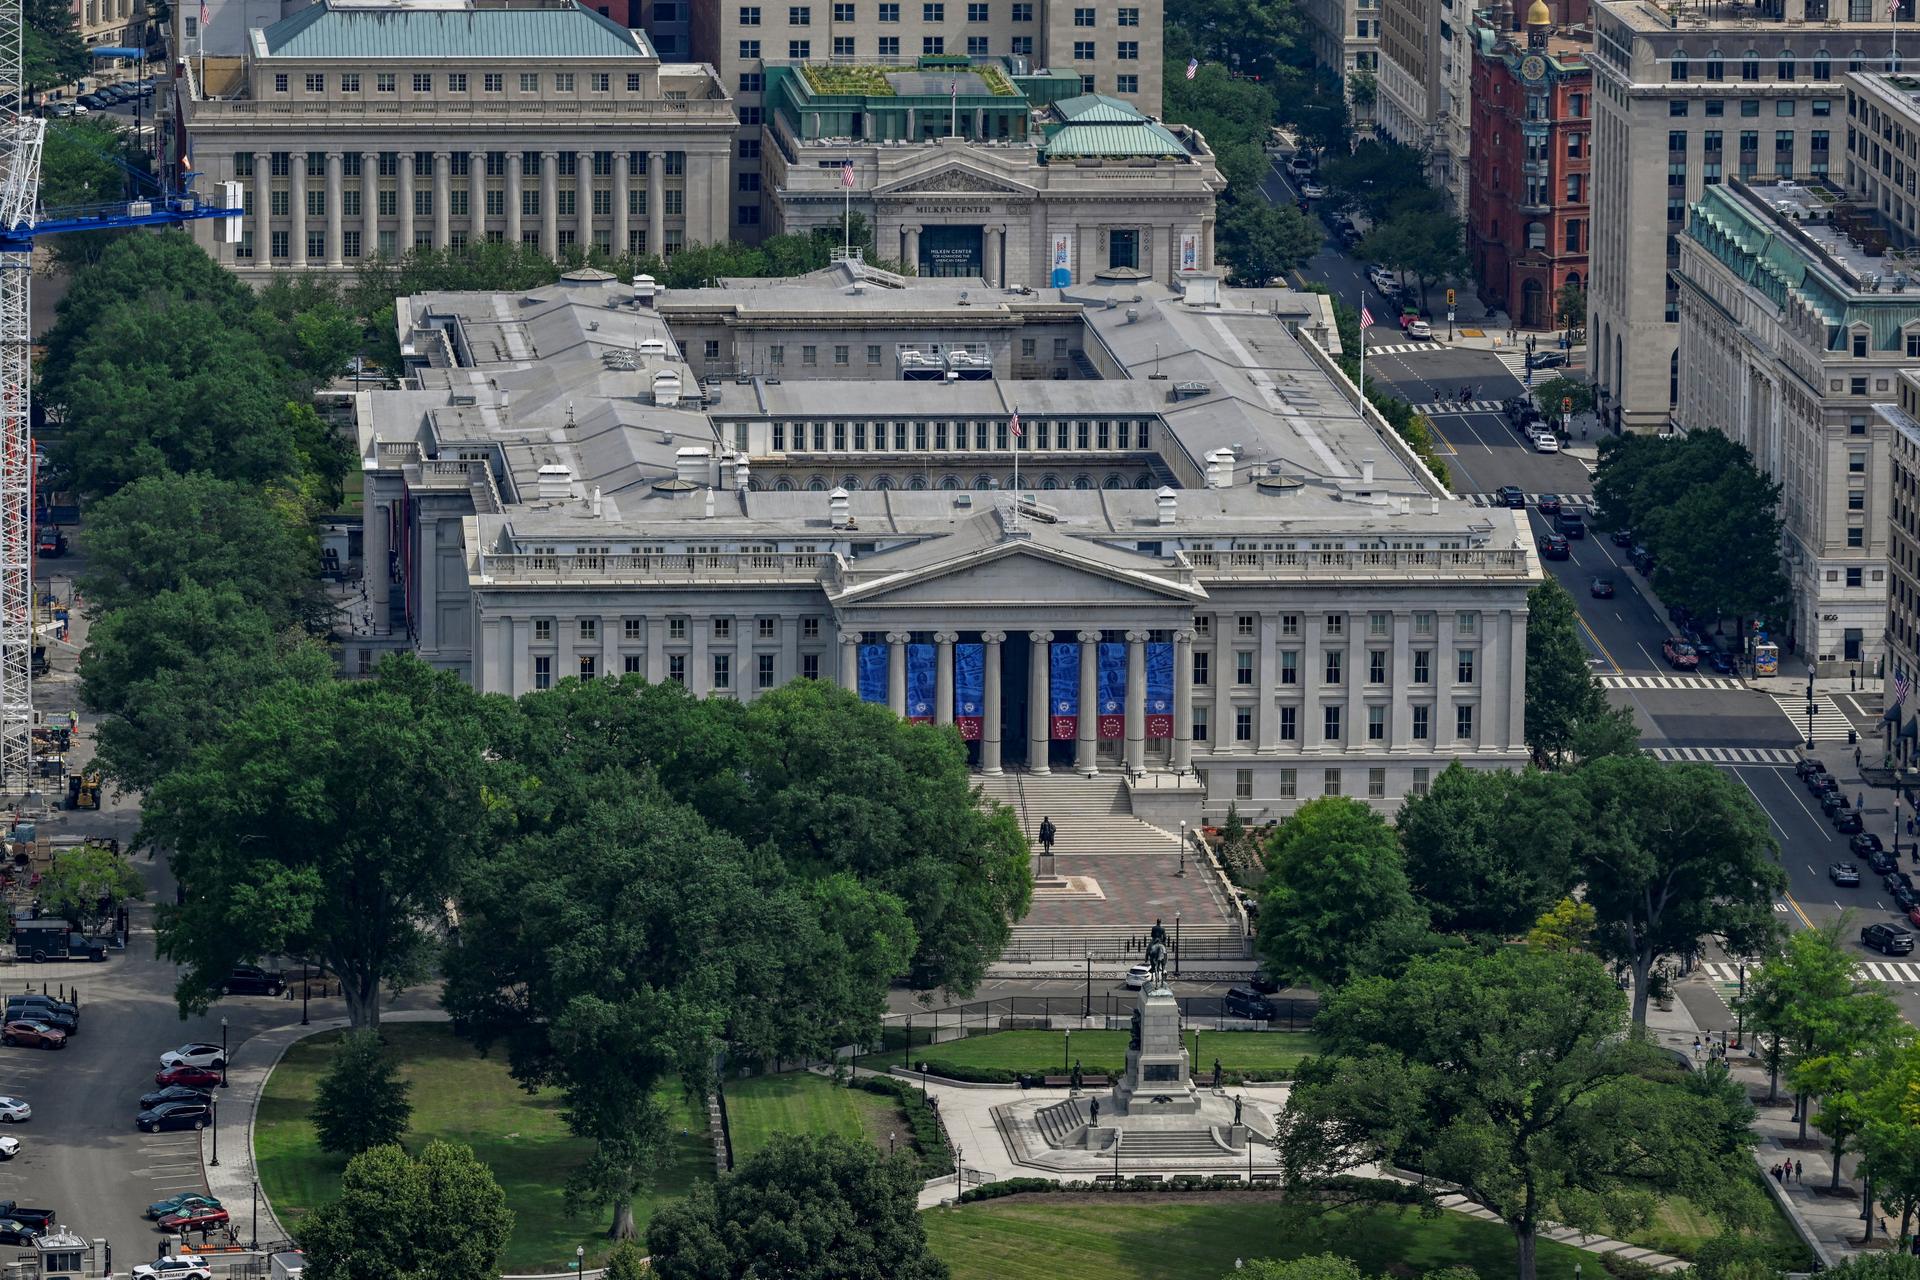
The US Department of the Treasury Building in Washington, D.C., U.S., July 11, 2026. REUTERS/Daniel Heuer/File Photo
|
Bonds have invariably taken the centre stage as the venue for market angst, with investors positioning for an era where interest rates stay higher for longer after a hawkish shift from major central banks in September.
Where has that left us? In a market where stocks are being propped up by the AI trade even as the massive investment needed for AI infrastructure leaves investors increasingly nervous while much of the action is being played out in bonds.
The yield on the benchmark 10-year US Treasury note has risen 81 basis points in the July-September quarter, on course for its steepest rise since 2022, pinning borrowing costs at a 19-year peak.
The clearest sign of this higher rates paradigm is in Japan. The yield on Japanese 10-year bond is up 42 bps in the quarter, set for its biggest rise in over two decades.
While rising yields have made government bonds attractive again for some investors, others remain cautious towards long-dated bonds given concerns about high government debt.
|
Graphics are produced by Reuters
|
|
|
|
New tests await in October |
Stcks, though, have largely shrugged off the impact of sky-high yields, mainly as investors pin their hopes on all things AI.
A slate of economic data later in the day will provide further clues on the state of the European economy and the monetary policy outlook. October will bring new tests in the shape of the latest US jobs and inflation data, French budget talks, a UK budget, and likely more bond issuance from tech firms.
|
|
|
|
Key developments that could influence markets on Wednesday: |
- Economic events: August retail sales for Germany, Q2 GDP data for UK, September CPI data for France, September CPI data for Germany
|
|
|
|
Opinions expressed are those of the author. They do not reflect the views of Reuters News, which, under the Trust Principles, is committed to integrity, independence, and freedom from bias.
|
|
|
|
|
|
| |
|
|
Morning Bid is sent every weekday morning. Think your friend or colleague should know about us? Forward this newsletter to them. They can also sign up here. Want to stop receiving this email? Unsubscribe here. To manage which newsletters you're signed up for, click here. This email includes limited tracking for Reuters to understand whether you’ve engaged with its contents. For more information on how we process your personal information and your rights, please see our Privacy Statement. Terms & Conditions |
|
| |
© 2026 Thomson Reuters. All rights reserved.
3 Times Square, New York, NY 10036 |
|
|
|
|
|





No comments:
Post a Comment